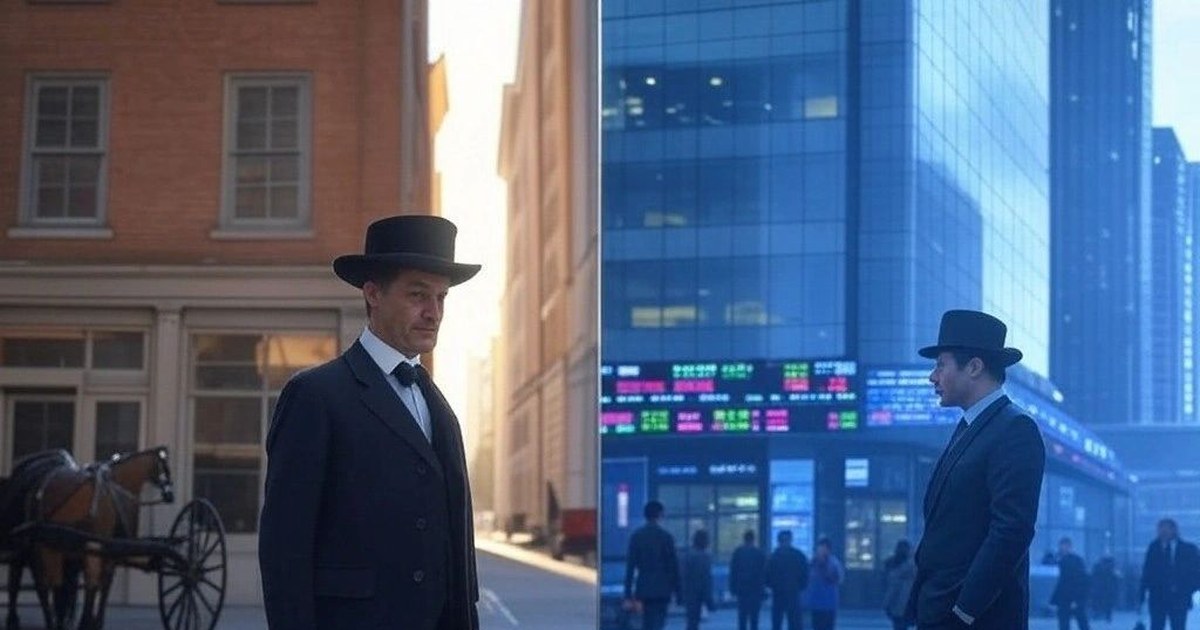
The digital free banking era marks a significant evolution in the financial sector, where traditional banking is being reshaped by technology, decentralization, and the advent of cryptocurrencies. This new era is characterized by:
- Decentralization: Unlike traditional banks, digital banking often operates on blockchain technology, offering a decentralized approach where financial transactions do not require intermediaries like conventional banks.
- Accessibility: Digital banking platforms and cryptocurrencies enable financial services to be more accessible to the unbanked or underbanked populations globally, providing tools for payment, saving, and lending without traditional banking infrastructure.
- Innovation in Financial Products: From smart contracts to decentralized finance (DeFi), digital banking introduces innovative financial products that allow for new types of investments, lending, and asset management.
- Regulatory Challenges: The rise of digital currencies and banking platforms outside traditional regulatory frameworks poses significant challenges for governments aiming to protect consumers, ensure financial stability, and prevent illicit activities.
- Consumer Empowerment: Users have more control over their financial data and can often choose from a variety of services tailored to their needs, often with lower fees due to the lack of overhead associated with physical branches.
The Free Banking Era in American History
The free banking era in the United States, which spanned from 1837 to 1863, offers a historical parallel to the current digital landscape:
- State Regulation: During this period, the federal government did not regulate banking; instead, states passed "free banking" laws, allowing virtually anyone to start a bank by depositing state bonds with state auditors. These bonds were meant to back the banknotes issued.
- Proliferation of Banks and Currencies: There was an explosion of banks, each issuing its own currency, leading to thousands of different banknotes, often traded at discounts depending on the perceived stability of the issuing bank.
- Lack of Uniformity and Stability: The absence of a central authority led to banknotes of varying reliability, causing significant inconvenience for commerce due to fluctuating values and frequent counterfeiting.
- Bank Failures: This era saw numerous bank failures due to speculative lending, inadequate reserve backing, and economic downturns, famously known for "wildcat banking," where banks were set up in remote areas to avoid scrutiny.
- Economic Lessons: The free banking era highlighted the need for some form of regulation to ensure stability, standardization, and public trust in currency, eventually leading to the National Banking Acts of 1863 and 1864.
Comparative Analysis Similarities:
- Innovation and Freedom: Both eras were driven by a spirit of innovation and freedom from stringent regulation, leading to a proliferation of new financial entities and models.
- Challenges with Stability: In both cases, the lack of centralized oversight led to issues with financial stability, whether it was through bank failures in the 19th century or the volatility of cryptocurrencies today.
- Consumer Choice: Each era provided consumers with more options for handling their finances, though with varying degrees of risk and complexity.
Differences:
- Technology: The digital era benefits from advanced technology, providing solutions like blockchain for security and transparency, which were not conceivable in the 19th century.
- Global vs. Local: Digital banking platforms operate on a global scale, unbound by geographical limitations, contrasting with the state-specific nature of the free banking era.
- Regulatory Response: Today, there's a proactive global conversation around regulating digital currencies, whereas the historical response was reactive, leading to the establishment of a more centralized banking system.
- Consumer Empowerment: Modern digital banking offers greater control over one's financial data and privacy, leveraging cryptography for security, something not available in the past.
- Economic Impact: While the free banking era was marked by local economic disruptions, the digital banking era potentially has broader implications, influencing global financial systems and policies.
Conclusion
The digital free banking era, while echoing the spirit of the American free banking period with its push for innovation and freedom from traditional constraints, operates in a vastly different technological and global context. This comparison highlights the timeless quest for financial freedom, but also the critical role of regulation in ensuring stability and trust in monetary systems. As we navigate this new era, lessons from history remind us to balance innovation with oversight to harness the full potential of digital finance for the benefit of all.